Key Account Stakeholder Mapping, Value Co-Creation and Strategic Growth
November 20, 2026 · Research · 8 min read
Written by MATSH Research & Editorial Team · Last updated
Strategic accounts grow when the supplier becomes more useful to the customer’s business, not when the account manager becomes better at pushing more products.
Value co-creation begins with evidence about what the customer is trying to achieve, what prevents it, what success is worth and which capabilities both organisations can combine. The account manager then turns that understanding into a portfolio of mutual-value initiatives and relationships strong enough to support them.
SAMA’s 2026 curriculum puts value co-discovery and quantification at the centre of strategic account management. Its current materials emphasise discovering what matters to customers, validating opportunities, aligning teams and enabling customer sponsors to articulate business value in their own language.
Source: SAMA, Co-Creation and Quantification of Value · Source: SAMA, Value Co-Creation, 2026
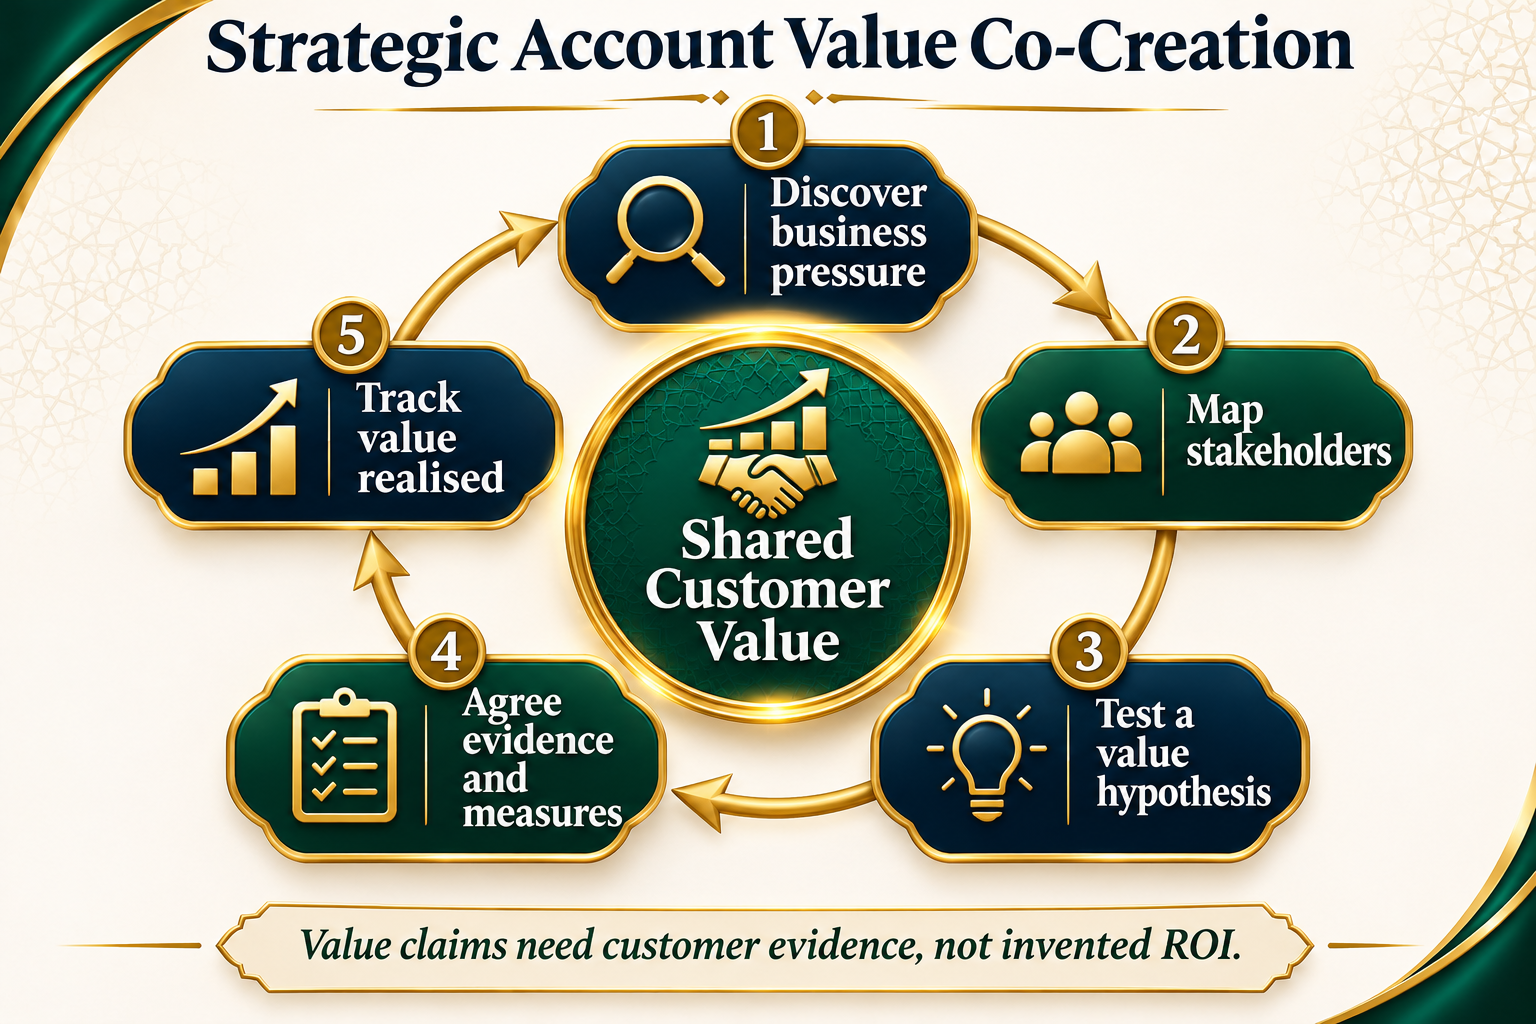
1. Start discovery with business pressure
| Pressure | Discovery question |
|---|---|
| Growth | Where is growth constrained? |
| Cost | Which operating costs matter most and why? |
| Risk | Which failures create material business impact? |
| Customer | Which customer outcomes need improvement? |
| Speed | Where does delay destroy value? |
| Capability | Which capability gap blocks strategy? |
2. Discover before proposing
The account team should understand the problem, current state, desired state, constraints and decision criteria before introducing a preferred solution.
Context
What is changing in the customer’s business?
Problem
Where is performance below desired state?
Impact
What does the gap cost or prevent?
Success
How would the customer recognise improvement?
3. Use multiple stakeholders to validate the problem
Finance, operations, IT and procurement may value the same initiative differently. A strategic account manager should test the hypothesis across the stakeholder network rather than relying on one sponsor’s interpretation.
Strategy and sponsorship
Budget and value case
Use, service and outcomes
Fit, risk and commercial process
A growth hypothesis is stronger when several stakeholder views confirm the same business problem.
4. Map stakeholder priorities
| Stakeholder | Possible value lens |
|---|---|
| CFO | Cash, cost, return, risk |
| COO | Throughput, reliability, service |
| CIO/CTO | Architecture, security, scalability |
| Business unit | Revenue, customer outcome, speed |
| Procurement | Total cost, terms, supplier risk |
5. Build a value hypothesis
Value hypothesis
- Customer priority
- Current performance/problem
- Proposed change
- Customer outcome expected
- Evidence required
- Stakeholders who must validate
- Assumptions
- Risks
6. Quantify value only where the evidence supports it
Downtime reduction
Current unplanned downtime is 120 hours per year. The customer estimates each hour creates an average 8,000 currency-unit contribution loss. A proposed maintenance model is expected to reduce downtime by 30 hours.
The initial value hypothesis is therefore tied to avoided downtime, but the account team must validate the customer’s cost assumption, technical feasibility and whether other constraints would still limit production.
7. Avoid supplier-created ROI theatre
Do not use exaggerated assumptions the customer cannot defend internally. SAMA’s current value material explicitly focuses on helping customer sponsors articulate value themselves.
8. Build a customer-owned value case
| Supplier claim | Customer-owned evidence |
|---|---|
| “Save 20%” | Customer baseline + agreed improvement measure |
| “Increase productivity” | Customer process metric |
| “Reduce risk” | Named risk event and impact |
| “Improve experience” | Customer-defined service/experience metric |
9. Separate price from value
Procurement may still negotiate price aggressively. Value discipline gives the supplier a stronger basis for discussing outcomes, trade-offs and total economics rather than responding only with discount.
10. Use a value portfolio
Evidence from current work.
Initiatives already underway.
Validated opportunities not yet committed.
Longer-term co-innovation possibilities.
11. Track value realization after sale
If the account team stops measuring when the deal closes, the next renewal starts without evidence. Create a value-realization plan with owners and customer measures.
Value realization fields
- Baseline
- Target
- Measurement owner
- Data source
- Review date
- Actual result
- Customer confirmation
- Next improvement
12. Use proof of delivered value in future discovery
SAMA’s current CORE 1 material highlights using historical value creation to support future co-discovery. Proven results reduce the need to restart every executive conversation from zero.
13. Build executive meetings around the customer’s agenda
| Weak executive meeting | Stronger meeting |
|---|---|
| Supplier presentation | Discussion of strategic customer priority |
| Product roadmap dump | Selective capability linked to customer agenda |
| Relationship courtesy call | Decision or insight the customer values |
14. Prepare executive sponsors internally
A supplier executive should understand the customer’s strategy, stakeholder history, current service issues, value delivered and meeting purpose before entering the conversation.
15. Map relationship gaps
Do we know more than one person?
Do we have access at the required seniority?
Are technical, operational, commercial and executive functions covered?
Do contacts advocate when we are not in the room?
16. Treat sponsor development as earned
A customer sponsor becomes an advocate because the supplier repeatedly creates useful outcomes, insight and trust. Do not label a friendly contact a sponsor without evidence of influence.
17. Build an internal influence map
| Customer stakeholder | Supplier counterpart | Objective |
|---|---|---|
| Customer COO | Supplier operations executive | Joint operating agenda |
| Procurement director | Commercial lead | Commercial transparency and terms |
| Technical lead | Solution architect | Architecture/innovation roadmap |
18. Use cross-functional account governance
Account lead
Owns plan, coordination and customer narrative.
Functional owners
Own delivery/value actions in their domain.
Executive sponsor
Supports strategic alignment and escalation.
Review cadence
Aligns opportunities, risks and commitments.
19. Separate service escalation from strategic dialogue
Key account managers often become the escalation desk. Service issues matter, but if every customer conversation is consumed by operational recovery, strategic discovery disappears.
20. Use service failures as value evidence
Recurring escalations can reveal process, technology or governance opportunities. Fix the root cause and quantify the improvement instead of simply closing tickets.
21. Track account economics by value stream
| Economic lens | Question |
|---|---|
| Revenue | What is current and forecast business? |
| Gross contribution | Does growth create profitable value? |
| Cost-to-serve | What resources does the account consume? |
| Discount leakage | Where is margin conceded without reciprocal value? |
| Working capital | Do payment/inventory terms create hidden cost? |
22. Manage concentration risk
A highly profitable strategic account can still create enterprise risk if it represents an excessive share of revenue, margin or specialist capacity. Track concentration alongside growth.
23. Build a retention risk score
Inputs can include:
- Value delivered
- Relationship breadth
- Executive sponsorship
- Service health
- Competitive activity
- Contract/tender timing
- Customer strategy change
- Price/value pressure
24. Use mutual action plans
For major initiatives, agree actions on both sides. Strategic value usually requires customer participation, data, process change or stakeholder access.
25. Review whether the relationship is becoming more strategic
| Signal | Evidence |
|---|---|
| Earlier involvement | Customer invites supplier before solution is fixed |
| Broader access | More relevant stakeholder relationships |
| Joint planning | Shared initiatives and measures |
| Value proof | Customer recognises quantified outcomes |
| Trust | Customer shares strategic context and constraints |
26. Do not confuse relationship warmth with strategic value
A friendly account can still be commercially weak, unprofitable or highly contestable. Use evidence about value, access, economics and mutual planning.
Common value-co-creation mistakes
27. Build a value-evidence hierarchy
| Evidence | Strength |
|---|---|
| Supplier estimate | Early hypothesis only |
| Customer operational data | Stronger baseline / result evidence |
| Jointly agreed calculation | Shared ownership of value logic |
| Customer finance validation | Strong evidence for executive/business case |
| Measured realised outcome | Best basis for future value conversations |
28. Create value baselines before implementation
If the account team waits until after delivery to prove value, it may discover that no trustworthy baseline exists. Agree the current-state measure before the initiative starts.
Service-response improvement
The customer wants “faster response”. The teams agree to baseline median response time, percentage within target and number of severe escalations for the prior quarter. After implementation they can compare the same measures instead of relying on anecdotal satisfaction.
29. Separate financial, operational and strategic value
Revenue, cost, cash, margin, working capital.
Speed, quality, uptime, productivity, capacity.
Probability/impact of material failure.
Market access, innovation, capability, customer differentiation.
30. Use ranges when value is uncertain
Do not force false precision. Where assumptions are uncertain, present a conservative/base/upper scenario and show which inputs drive the difference.
31. Track value leakage
| Leakage | Example |
|---|---|
| Scope creep | Extra work delivered without commercial/value recognition |
| Low adoption | Solution capability exists but customer use is weak |
| Delayed customer action | Value depends on process change the customer has not implemented |
| Discounting | Supplier gives away part of the value before it is recognised |
32. Use joint value-realisation reviews
Review:
- Expected outcome
- Actual result
- Customer evidence
- What enabled / blocked value
- Value leakage
- Next improvement
- Potential next co-creation opportunity
33. Distinguish advocacy from satisfaction
A satisfied contact may still not influence decisions. A true sponsor can explain the supplier’s value to internal stakeholders, help navigate the organisation and support strategic initiatives.
34. Use sponsor coverage by initiative
| Initiative | Operational sponsor | Economic sponsor | Executive support |
|---|---|---|---|
| Service redesign | Operations director | CFO/BU finance | COO |
| Technology transformation | IT leader | Business sponsor | CIO/CEO depending scale |
35. Protect account profitability during customisation
Strategic accounts often request tailored features, reporting and service. Track whether customisation is funded, repeatable, strategically useful or simply adding hidden cost-to-serve.
36. Use reciprocal commitments
If the supplier invests heavily, define the customer actions required to realise value, such as data access, process adoption, executive participation or implementation resources.
37. Review the account as an investment portfolio
For each initiative, ask:
- Customer value potential
- Supplier commercial value
- Investment required
- Probability of success
- Time to value
- Strategic learning/positioning
- Risks and dependencies
38. Stop low-value initiatives
Strategic account teams often keep pet projects alive because senior stakeholders once liked them. Kill initiatives that no longer create customer or supplier value and redirect resources.
Make customer value visible enough to grow the relationship
MATSH’s Key Account Management Course covers stakeholder networks, value co-discovery, value quantification, executive engagement, cross-functional governance, account economics and retention.
Explore Sales, Customer Relations & Negotiation
Explore the Key Account Management course
Register
Sources
Need In-House Training?
We run all our courses as private programmes for organisations across the GCC and Africa.
Request In-House →